SBA 7(a) or 504 for a motel: 10% down with a floating rate, or 15% down with part of the rate fixed

The SBA approved 764 loans under its 7(a) program and 382 under its 504 program to hotels and motels in federal fiscal 2025, by our count of the agency’s public loan file [1]. The 7(a) loans came to $2.05 billion. The 504 loans added $1.03 billion of SBA-backed debentures on top of $1.76 billion in bank first loans [1].
If you are shopping hotel financing for a small hotel or motel, the program you pick sets three things: the cash you bring to closing, whether your rate moves with prime, and the fees. A bank loan without the SBA is the third path, and no bank publishes its price.
Motel4 publishes this post. We sell an AI phone receptionist, not loans, and have no tie to any lender. The rules below come from the SBA’s lending manual, SOP 50 10 8.1, in effect since Oct 1, 2026 [2].
We counted every fiscal 2025 loan coded NAICS 721110, hotels and motels, in the SBA file, read the manual’s rules for hotels, and priced one $2.8 million motel purchase through each path. Our notes on how we write explain how every number was checked.
Prices, checked Oct 21, 2026
Loans have no sticker price, so this table lists the rules that set one for a hotel loan over $350,000. Prime was 7.00% and the 10-year Treasury 5.15% on Oct 19 [3].
| Loan | How the rate is set | Today’s number | Cash down for a hotel | Longest term | Upfront fees | Source |
|---|---|---|---|---|---|---|
| SBA 7(a), variable rate | Prime plus up to 3 points | 10.00% cap | 10% | 25 years with the real estate | Up to 3.5% of the guaranteed part, 3.75% above $1 million of it | [2][3] |
| SBA 7(a), fixed rate | SBA’s monthly maximum | 12.00% cap for October | 10% | 25 years with the real estate | Same as variable | [4][2] |
| SBA 504, CDC debenture | Fixed, an increment over the 10-year Treasury | Treasury at 5.15% | 15%, or 20% for a new business | 25 years | About 3% of the debenture, can be financed | [5][2][3] |
| SBA 504, bank first loan | Set by the bank | Not published | Counted in the row above | At least 10 years | Set by the bank | [2] |
| Bank loan alone | Set by the bank | Not published | Set by the bank | Set by the bank | Set by the bank | [2] |
What hotel owners actually paid sits well under the caps. In fiscal 2025, 96% of hotel 7(a) loans had a variable rate, and the median was 1.25 points over prime [1]. The most common spread, on 248 loans, was 1 point. Fewer than 1% of variable-rate hotel loans over $350,000 sat at the 3-point cap [1].
SBA 7(a) carries most SBA-backed motel purchases: 10% down, and the rate floats with prime
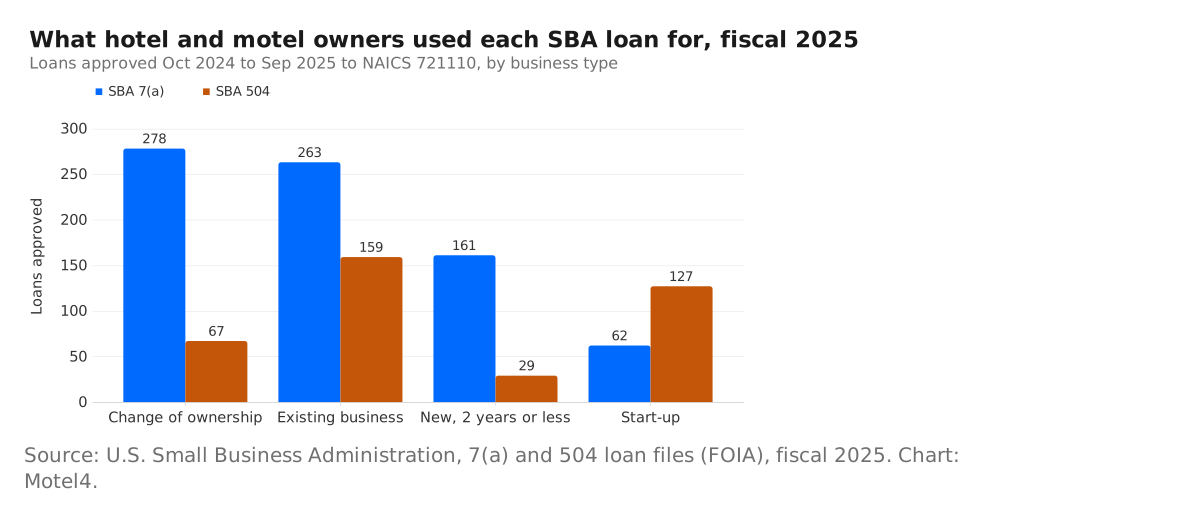
Who it fits: a buyer taking over a running motel. Of the 764 hotel 7(a) loans in fiscal 2025, 278 were changes of ownership, against 67 of the 382 504 loans [1]. A 7(a) loan tops out at $5 million [6].
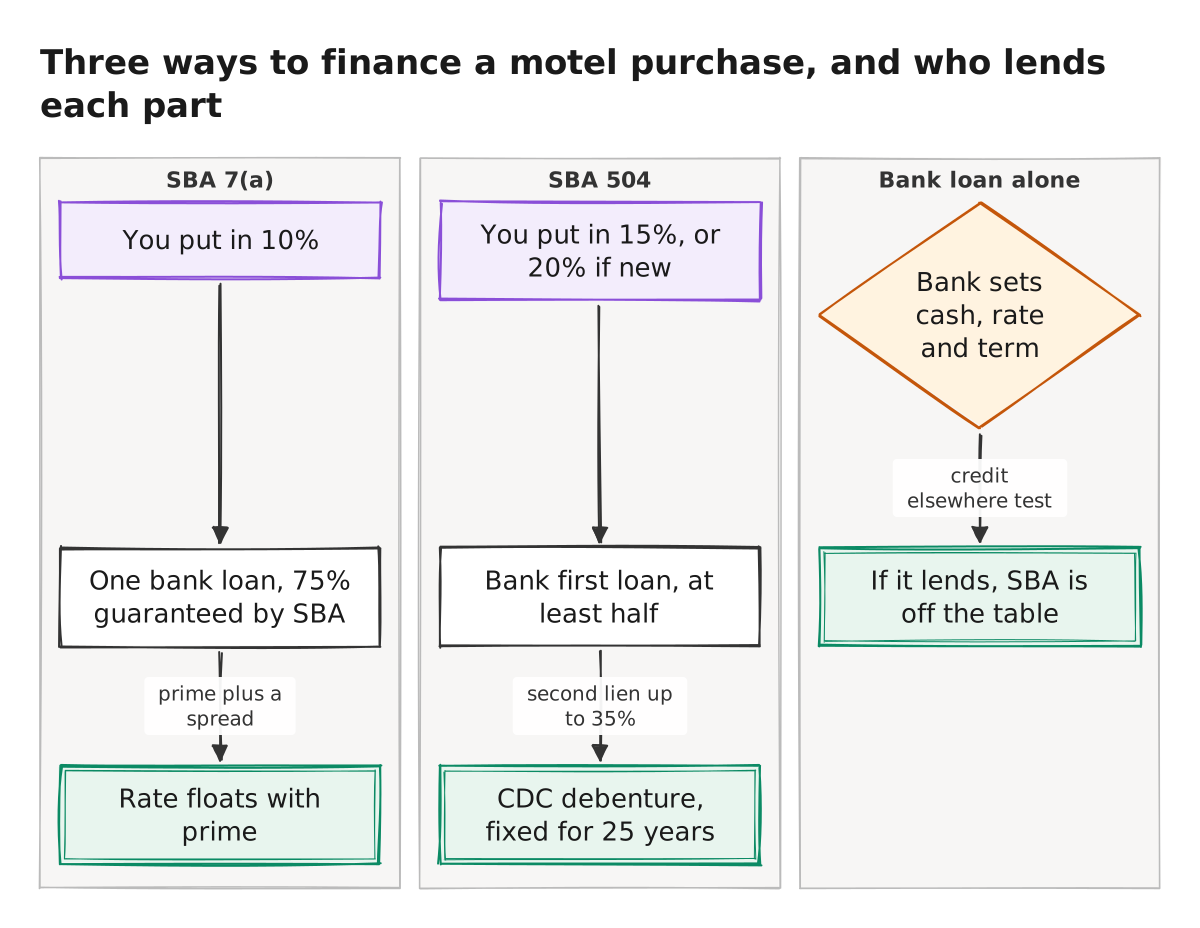
What it costs: the manual sets 10% down for an initial acquisition, and says that amount “cannot be reduced or eliminated” [2]. A lender may stretch the loan to 25 years when 85% or more of the project cost is real estate, and the manual names hotels as an example [2]. In fiscal 2025, 82% of hotel 7(a) loans ran 300 months [1].
The upfront guaranty fee is charged on the SBA’s 75% share of the loan: up to 3.5% on the first $1 million of that share and 3.75% above it [2]. On a $2.52 million loan that is up to $68,375, and you may pay it from the loan proceeds [2].
Watch out for: the floating rate, and an early payoff fee. Prepay more than 25% of a loan of 15 years or longer in its first three years and you owe 5%, 3% or 1% of the prepaid amount, by year [2].
The lender also tests that the motel’s cash flow covers the payment 1.25 times, and checks your tax returns against IRS transcripts [2].
SBA 504 suits building or adding rooms: 15% down and a fixed rate on part of the loan
Who it fits: an owner building a hotel, adding rooms, or buying the property under a business already running. Start-ups took 127 of the 382 hotel 504 loans in fiscal 2025, a third, against 62 of the 764 7(a) loans [1].
What it costs: a 504 splits the price three ways. The SBA lists hotels and motels as special purpose property, so you put in at least 15%, a certified development company (CDC) lends up to 35%, and a bank lends at least 50% [2].
A new business puts in 20%, and the CDC’s debenture is capped at $5 million per business [2].
In fiscal 2025 the median hotel 504 debenture was $2,424,000 and the median bank first loan $3,721,516. Of the 382 loans, 372 ran 25 years [1].
The debenture rate is fixed for the term and pegged to an increment above the 10-year Treasury, which stood at 5.15% on Oct 19 [5][3]. Its fees total about 3% and can be financed [5]. The manual’s worked example lists a 0.5% SBA guaranty fee, a 0.25% funding fee and a 1.5% CDC processing fee [2].
Watch out for: the bank’s half. The manual lets that first loan run as short as 10 years under a 25-year debenture, so get its rate, term and any balloon in writing [2]. A 504 cannot pay for working capital or inventory [5], and paying it off early costs a fee the manual calls a repurchase premium [2].
Hotel financing without the SBA has no public price, and the SBA wants you to try it first
Banks set their own down payment, rate and term for a hotel loan, and none publish them. The SBA does publish the rule that links the two [2].
An SBA lender must certify you cannot get the credit on reasonable terms elsewhere. If your cash flow and collateral meet the bank’s conventional standards, “the Project is not eligible for an SBA Loan” [2].
The manual lists the reasons a bank’s own policy says no: you need a longer term than it allows, the loan is above its limit for one customer, the collateral falls short, or it does not lend to new businesses or to your industry [2]. Lenders also look at the cash of anyone who owns 20% or more of the business [2].
So ask your bank for a conventional quote first. If it lends, compare its down payment and term with the rows above. If it declines, its reasons are part of the file an SBA lender has to build.
The math for a $2.8 million motel: $19,869 a month on a 7(a) loan
We picked a price that puts the 7(a) loan, $2.52 million, near the fiscal 2025 median hotel loan of $2,548,250 [1]. The rate is today’s 7.00% prime [3] plus the 1.25-point median spread [1], or 8.25%, over 25 years.
That is $238,428 a year. At the 1.25 coverage test, the motel needs about $298,035 a year of cash flow before the loan payment to qualify [2]. Because the rate floats, the payment moves with prime:
| Case | Prime | Your rate | Monthly payment | Change from today |
|---|---|---|---|---|
| Low | 6.00% | 7.25% | $18,215 | $1,654 less |
| Mid (today) | 7.00% | 8.25% | $19,869 | none |
| High | 8.00% | 9.25% | $21,581 | $1,712 more |
| SBA cap, prime plus 3 | 7.00% | 10.00% | $22,899 | $3,030 more |
The same purchase on a 504 needs $420,000 down, $140,000 more than the 7(a), or $560,000 for a new business [2]. With the bank at 50% and the CDC at 35%, they lend $1.4 million and $980,000, plus about $29,400 of CDC fees that can be financed [5].
We could not confirm this month’s 504 debenture rate from a public page, or whether the SBA has cut the 7(a) upfront fee for fiscal 2027; the manual lets it change fees for a year by notice [2]. Ask your lender and CDC for both in writing.
The math also assumes the whole price qualifies for 25 years. Goodwill and working capital in a purchase get a shorter, blended term [2].
Verdict
Pick SBA 7(a) if you are buying a running motel and cash is the limit: 10% down, one lender, and a payment that moves $1,654 to $1,712 a month for each point of prime on a $2.52 million loan.
Choose SBA 504 if you are building, adding rooms or buying the real estate under a business you already run, and can bring 15% to fix the rate on up to 35% of the price. Use a bank loan alone if your bank offers one you can carry, because SBA rules leave you no other option.
The fiscal 2025 file shows how hotel owners chose: 7(a) for buying a running motel, 504 more often for start-ups [1]. Get the conventional quote first, then ask an SBA lender and a CDC for written terms on the same price. If the motel is new to you, set up the phone system for opening day before the keys change hands.
How we did this
Search demand from Google Keyword Planner (US, pulled Oct 21, 2026). Loan counts, sizes, terms and rate spreads computed by Motel4 from the SBA's 7(a) and 504 FOIA loan files as of June 30, 2026, for NAICS 721110, hotels and motels. Lending rules from SBA SOP 50 10 8.1, effective Oct 1, 2026. Rates from the Federal Reserve's H.15 release of Oct 20, 2026 and the SBA's FTA Wiki, checked Oct 21, 2026. Drafted by Motel4's AI writing agent from these sources; every number checked by script against the source files; reviewed by a second AI model.
Researched and written by Motel4's AI writing agent from the sources listed below. Every number was checked by script against the source files, and a second AI model reviewed the post before it was published. The Motel4 Team is responsible for this page.
Sources
- U.S. Small Business Administration, 7(a) and 504 FOIA loan data, as of June 30, 2026 (primary source), accessed Oct 21, 2026.
- U.S. Small Business Administration, SOP 50 10 8.1, Lender and Development Company Loan Programs, effective Oct 1, 2026 (primary source), accessed Oct 21, 2026.
- Board of Governors of the Federal Reserve System, H.15 Selected Interest Rates, release of Oct 20, 2026 (primary source), accessed Oct 21, 2026.
- U.S. Small Business Administration, FTA Wiki: October 2026 maximum allowable fixed rate for 7(a) loans (primary source), accessed Oct 21, 2026.
- U.S. Small Business Administration, 504 loans (primary source), accessed Oct 21, 2026.
- U.S. Small Business Administration, 7(a) loans (primary source), accessed Oct 21, 2026.
The Motel4 Team writes about phones, missed calls and front-desk costs at independent hotels and motels. Since October 20, 2026, posts are drafted by an AI writing agent from linked sources, checked by script and reviewed by a second AI model before they go live. How we write. To reach us or report an error: motel4.ai/contact.